Investment property loan
Investment Property Loans
Finance Structured for Property Investors
Whether you’re purchasing your first investment property or expanding an established portfolio, the right finance structure can make a significant difference to your long-term strategy.
At Kesh Finance Solutions, we help property investors navigate lending options across banks, non-bank and specialist lenders. We focus on structuring finance around your investment goals, borrowing position and future plans — not simply finding the lowest advertised rate.
The Right Finance Structure Matters
Investment lending isn’t only about the interest rate. Different lenders can assess your income, existing debts, rental income, property type and borrowing capacity differently.
The way your loans are structured today may also affect your ability to refinance, access equity or purchase another property in the future.
We help you explore lending options and structure your finance around both your current investment purchase and your longer-term property plans.
How Investment Loans Differ from Owner-Occupied Home Loans
Deposit & Equity Requirements Vary by Lender
Different Lending & Servicing Criteria
Flexible Repayment Options, Including Interest-Only
Investment Loan Rates Are Typically Higher
Key Finance Considerations for Property Investors
Use Home Equity to Fund Your Investment Loan
- Use Available Equity Towards Your Deposit
- Potentially Reduce the Need for LMI
- Preserve More of Your Cash Savings
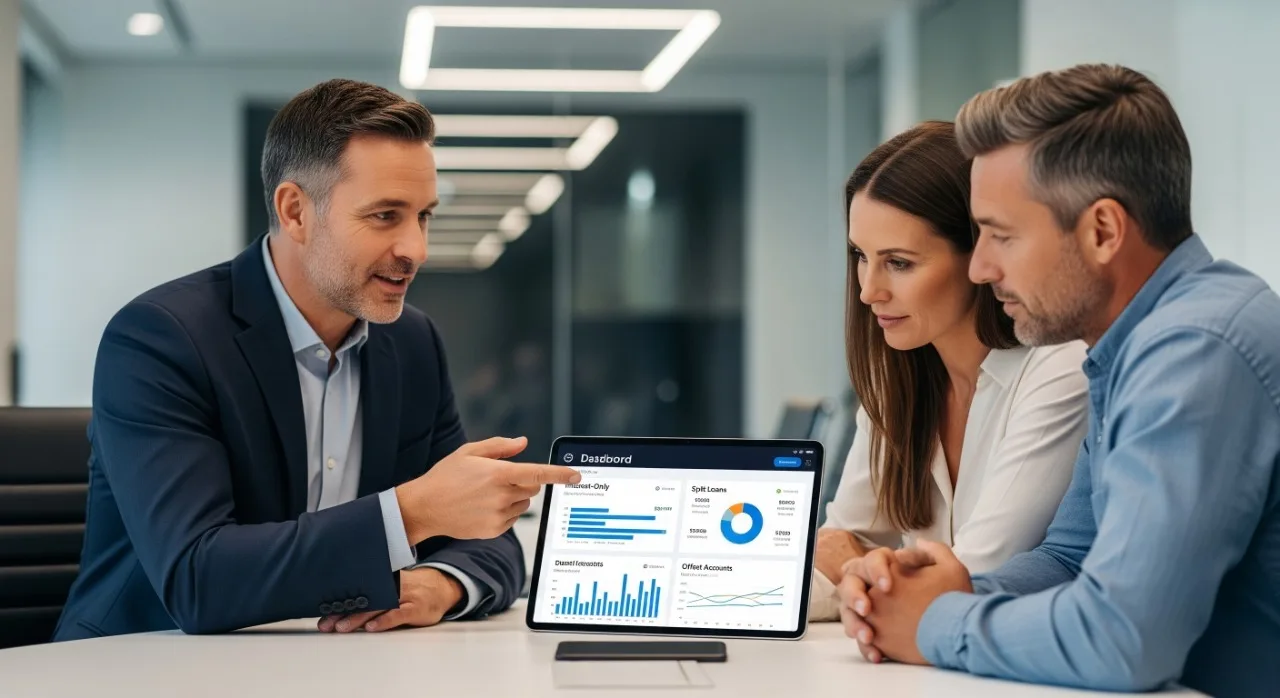
Structure the Loan to Support Your Investment Goals
- Principal & Interest or Interest-Only Options
- Fixed, Variable or Split Loan Options
- Offset & Redraw Features Where Available
Tailor Your Loan to the Investment Property Type
- Different Lender Policies for Different Property Types
- Rental Income Assessment Varies by Lender
- Property Valuation & LVR Requirements
Note: Lending criteria, borrowing capacity and available options vary between lenders. We’ll help you understand which options may suit your circumstances and investment strategy.
How We Can Help You
At Kesh Finance Solutions, we help property investors navigate lending options across banks, non-bank and specialist lenders. We focus on finding a finance structure that supports your investment goals, borrowing position and future plans.
Compare Investment Loan Options
Access Bank, Non-Bank & Specialist Lenders
Structure Finance Around Your Investment Goals
No matter your experience level, we simplify the finance process and help you make informed decisions as your property portfolio grows.
Investment Finance Solutions
Whether you’re purchasing your first investment property, expanding your portfolio or refinancing an existing investment loan, we can help you explore finance options suited to your circumstances.
- Residential investment properties (houses, units, townhouses)
- Dual occupancy properties
- Portfolio Expansion & Equity Release
- Investment Property Refinancing
- Non-Resident & Expat Investment Loans
What Determines Your Investment Loan Options?
- Loan-to-Value Ratio (LVR)
- Income & Borrowing Capacity
- Property Type & Rental Income
- Loan Structure & Repayment Type
- Lender Policy & Eligibility
Why Choose Kesh Finance Solutions?
30+ Years of Experience
Extensive finance experience helping clients navigate lending options and structure finance around their goals.
Broader Lending Options
Access to bank, non-bank and specialist lenders allows us to explore different lending policies and finance structures to find options suited to your investment goals and circumstances.
Personalised, Ongoing Support
From assessing your options through to approval and settlement, we guide you throughout the finance process.
Frequently Asked Questions
The deposit required will depend on the lender, property type and your financial position. While a 20% deposit is common, some lenders may consider a lower deposit. If you already own property, available equity may also be used towards the purchase.
Yes. Lenders generally consider expected rental income when assessing an investment loan, but they may not use 100% of the rent. Different lenders also assess rental income and borrowing capacity differently, which is why choosing the right lender can make a significant difference.
It depends on your investment strategy, cash flow and longer-term objectives. Interest-only repayments can reduce your repayments for an initial period, but your loan balance does not reduce and repayments generally increase when the interest-only period ends.
Both established and new properties can be suitable investments depending on your goals, borrowing position and investment strategy. New and established properties can have different tax considerations, while location, price, rental income and lender requirements can also differ. We can help you understand the finance options, but you should seek independent tax and property advice before making an investment decision.
From 1 July 2027, the tax treatment of residential property investment will change. Negative gearing will generally continue for eligible new builds and properties covered by the grandfathering arrangements. For established residential properties acquired after 7:30pm AEST on 12 May 2026, rental losses generally cannot be deducted against other income such as salary, although they may be used against residential property income or carried forward, subject to the rules.
Capital gains tax rules are also changing from 1 July 2027. As tax outcomes depend on your individual circumstances, we recommend obtaining advice from a qualified tax professional before making an investment decision.
Yes. Lenders can treat rental income, investment property expenses and negative gearing differently when assessing borrowing capacity. As lender policies and servicing calculations vary, the amount you may be able to borrow can differ from one lender to another.
We can compare lender policies and servicing outcomes to help identify finance options suited to your borrowing position and investment plans.
Ready to Discuss Your Investment Finance Options?
Let’s discuss your investment goals and explore finance options that support your borrowing position and longer-term property strategy.